A non-recourse loan lets your self-directed IRA buy more property than it could with cash alone — and it brings one tax rule to understand before you close: UBIT on debt-financed income. It’s usually manageable, often costs little each year, and your IRA pays it, not you.
The short version
When dealing with leveraged real estate in a retirement account, you will frequently encounter these three acronyms. Here is how they relate to one another:
Bought with cash
No annual tax return
Rental income and gains grow tax-deferred, or tax-free in a Roth IRA.
Bought with a loan
The loan’s share can be taxed
Income tied to the loan is Unrelated Debt-Financed Income (UDFI) and may be subject to Unrelated Business Income Tax (UBIT).
1
Your IRA files Form 990-T in any year its gross debt-financed income is $1,000 or more.
2
Any tax is paid from IRA funds, never your personal account.
3
When you sell, part of the gain can be taxable if there was debt on the property anytime in the 12 months before the sale.
Do I have to file every year?
Usually yes, while the loan is in place.
The filing threshold is based on gross debt-financed income, not net profit. A typical single-family rental with a meaningful loan will cross $1,000 most years. That doesn’t mean you’ll owe much. The IRA can deduct the debt-financed share of:
Mortgage interest
Property taxes
Insurance
Repairs and maintenance
Management fees
Straight-line depreciation
It also gets a $1,000 specific deduction. Many leveraged rentals show little or no taxable income after these.
Why file even when nothing is owed? Filing the 990-T each year records any losses so they can be carried forward and used against the taxable gain when you sell.
Who files, and who pays?
| The return | Form 990-T is filed for the IRA, typically through or with the approval of your custodian. It does not go on your personal 1040. |
| The tax | Paid from the IRA. Paying it personally could be treated as a contribution or a prohibited transaction. |
| IRA-owned LLC | If your IRA owns 100% of the LLC, it’s typically a disregarded entity with no separate return. With more than one member, the LLC files a partnership return (Form 1065) every year. |
| Title in the LLC | Doesn’t change the UBIT rules. Debt-financed income is taxed the same whether the IRA or its LLC holds title. |
| State | Your state may require its own return. |
What happens when I sell?
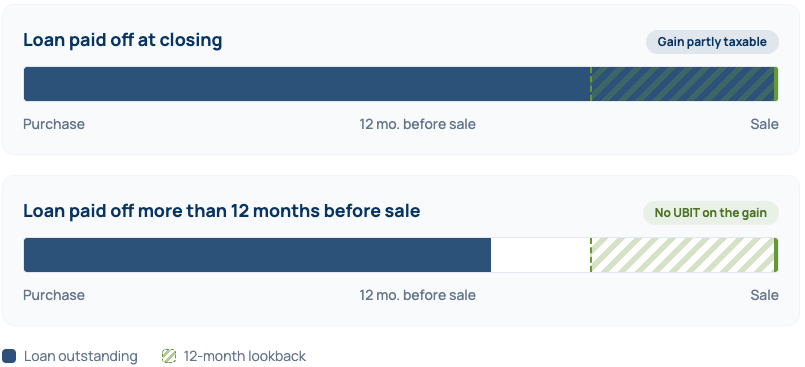
This is the part most investors miss. The taxable share of the gain is based on the highest loan balance during the 12 months before the sale. UBIT is taxed at trust tax rates, which reach the top bracket at a relatively low income level, so plan the exit early.
Losses carried forward from earlier 990-T filings can also reduce the taxable gain.
A simple example
A $200,000 single-family rental bought with $80,000 from the IRA and a $120,000 non-recourse loan.
| Purchase price | $200,000 |
| IRA cash down payment | $80,000 |
| Non-recourse loan | $120,000 |
| Debt-financed percentage | 60% |
| Annual gross rent | $24,000 |
| Gross debt-financed income (60%) 990-T required | $14,400 |
| Total deductions: interest, taxes, insurance, repairs, depreciation | $21,218 |
| Debt-financed share of deductions (60%) | −$12,731 |
| Specific deduction | −$1,000 |
| Taxable UBTI | $669 |
The IRA files a 990-T but owes tax on only a few hundred dollars of income, while all $24,000 of rent flows into the IRA.
Is the tax worth it?
For many investors, yes. Even after UBIT, the return on the IRA’s cash from a leveraged property often beats an all-cash purchase. Run the numbers on your deal before deciding.
Buy more property
Purchase a home your IRA couldn’t afford with cash alone.
Diversify
Spread your IRA’s cash across more than one property.
Raise your return
Earn more on each dollar of IRA cash you put in.
Self-employed? Certain qualified plans, such as a Solo 401(k), are generally exempt from UDFI on real estate when specific requirements are met. Ask your tax advisor whether that fits you.
Keep your IRA in compliance
The loan must be non-recourse, with no personal guarantee from you.
All expenses are paid from the IRA, and all income goes back to the IRA.
You and other disqualified persons can’t live in, rent, or personally use the property.
Give your custodian a year-end fair market value each year for Form 5498.
Frequently Asked Questions
No. The IRA pays any UBIT from its own funds.
No. An IRA-owned LLC is treated the same as the IRA for these rules.
No. Roth IRAs follow the same debt-financed income rules.
No. The loan must be paid off more than 12 months before the sale.
Losses can be carried forward on the 990-T to offset future income or gain, which is one more reason to file every year.
Disclaimer: This information is for general educational purposes only and is not tax, legal, or investment advice. IRA Loans Made Easy does not provide tax or legal advice. Tax rules are complex and may change. Consult a qualified CPA or tax attorney familiar with self-directed IRAs before making any investment decision.
I hope this helped. Any questions related and tax questions, please contact your tax advisor or CPA.
IRA Loans Made Easy is only a consultant and not a loan officer. We have no ability to approve loans nor will be privy of any personal information as it is related to any lender documentation.